Meine Buchnotizen – The Millionaire Next Door von Thomas Stanley und William Danko
Thomas Stanley und William Danko haben die Millionäre in den USA vom wissenschaftlichen Standpunkt untersucht und dabei erstaunliche Sachen herausgefunden. So unterscheidet sich der typische Millionär erheblich von dem Bild, welches von den Medien vermittelt wird.
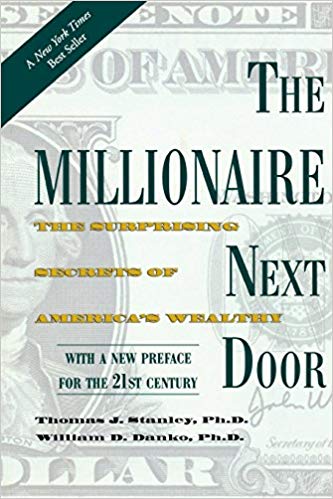 Gelesen im Juli 2017. Auf der Amazon Seite finden Sie mehr Details und Rezensionen. Wenn Sie es nicht so mit dem Lesen haben, empfehle ich Ihnen Audible auszuprobieren. Audible ist im ersten Monat kostenlos und Sie können dort fast alle Bücher auch als Hörbuch hören. Ich will Audible nicht mehr missen.
The advertising industry and Hollywood have done a wonderful job conditioning us to believe that wealth and hyperconsumption go hand in hand. Yet, the large majority of the rich live well below their means. Unfortunately, most Americans think that they are emulating the rich by immediately consuming any upward swing in their cash flow.
We discovered something odd. Many people who live in expensive homes and drive luxury cars do not actually have much wealth. Then, we discovered something even odder: Many people who have a great deal of wealth do not even live in upscale neighborhoods.
Wealth is not the same as income. If you make a good income each year and spend it all, you are not getting wealthier. You are just living high. Wealth is what you accumulate, not what you spend.
Cars tend to depreciate rapidly. Financial assets tend to appreciate.
„Big Hat No Cattle“ – I don’t own big hats, but I have a lot of cattle.
It is seldom luck or inheritance or advanced degrees or evenintelligence that enables people to amass fortunes. Wealth is more often the result of a lifestyle of hard work, perseverance, planning, and, most of all, self-discipline.
80% of America’s millionaires are first-generation rich.
- They live well below their means.
- They allocate their time, energy, and money efficiently, in ways conducive to building wealth.
- They believe that financial independence is more important than displaying high social status.
- Their parents did not provide economic outpatient care.
- Their adult children are economically self-sufficient.
- They are proficient in targeting market opportunities.
- They chose the right occupation.
Interestingly, self-employed people make up less than 20 percent of the workers in America but account for two-thirds of the millionaires. Three out of four who are self-employed consider ourselves to be entrepreneurs. Most of the others are self-employed professionals, such as doctors and accountants.
The typical household’s total annual realized (taxable) income is $131,000 (median, or 50th percentile). The typical (median, or 50th percentile) millionaire household has a net worth of $1.6 million.
On average, millionaire’s total annual realized income is less than 7 percent of their wealth. In other words, they live on less than 7 percent of their wealth.
Millionaires have a “go-to-hell fund.” [FU Money] In other words, they have accumulated enough wealth to live without working for ten or more years. Thus, those of them with a net worth of $1.6 million could live comfortably for more than twelve years. Actually, they could live longer than that, since they save at least 15 percent of our earned income.
As a group, millionaires believe that education is extremely important for themselves, their children, and their grandchildren. Millionaires spend heavily for the educations of their offspring.
About two-thirds of millionaires work between forty-five and fifty-five hours per week.
Millionaires are fastidious investors. On average, millionaires invest nearly 20 percent of their household realized income each year.
Millionaires make their own investment decisions.
“I am my favorite charity.”
Multiply your age times your realized pretax annual household income from all sources except inheritances. Divide by ten. This, less any inherited wealth, is what your net worth should be.
How much money does it take to maintain the upper-middle-class lifestyle of an attorney and his family?
How much money is required to maintain the middle-class or even blue-collar lifestyle of a mobile-home dealer and his family?
Clearly, the attorney must spend significantly more of his household’s income to maintain and display his family’s higher upper-middle-class lifestyle.
Most people who become millionaires have confidence in their own abilities. They do not spend time worrying about whether or not their parents were wealthy.
Self-employment is a major positive correlate of wealth.
„I drink scotch and two kinds of beer — free and Budweiser!“
Allocating time and money in the pursuit of looking superior often has a predictable outcome: inferior economic achievement.
What are three words that profile the affluent? FRUGAL FRUGAL FRUGAL
Most people want immediate gratification.
Millionaires became millionaires by budgeting and controlling expenses, and they maintain their affluent status the same way.
Over the past five years her annual income averaged around $90,000. But her net worth keeps increasing. Today Mrs. Rule has a net worth of more than $2 million.
QUESTION 1: DOES YOUR HOUSEHOLD OPERATE ON AN ANNUAL BUDGET?
QUESTION 2: DO YOU KNOW HOW MUCH YOUR FAMILY SPENDS EACH YEAR FOR FOOD, CLOTHING, AND SHELTER?
QUESTION 3: DO YOU HAVE A CLEARLY DEFINED SET OF DAILY, WEEKLY, MONTHLY, ANNUAL, AND LIFETIME GOALS?
QUESTION 4: DO YOU SPEND A LOT OF TIME PLANNING YOUR FINANCIAL FUTURE?
There are worse things than a budget, such as never being able to retire and never being financially independent. It’s much easier to budget if you visualize the long-term benefits of this task.
Only those clients with considerable wealth want to know exactly how much their family spends on each and every category.
Financially independent people are happier than those in their same income/age cohort who are not financially secure.
To build wealth, minimize your realized (taxable) income and maximize your unrealized income (wealth/capital appreciation without a cash flow).
It’s easier to accumulate wealth if you don’t live in a high-status neighborhood. But even those millionaires who do live in high-status areas realize only 6.7 percent of their wealth each year.
Even if you’re earning $100,000 a year, you’re not becoming wealthy. What you probably don’t know is that your neighbor in the $300,000 house next to yours bought his house only after he became wealthy. You bought yours in anticipation of becoming wealthy. That day may never come.
If you’re not yet wealthy but want to be someday, never purchase a home that requires a mortgage that is more than twice your household’s total annual realized income.
There is an inverse relationship between the time spent purchasing luxury items such as cars and clothes and the time spent planning one’s financial future.
Overall, PAWs (Prodigious Accumulator of Wealth) have significantly fewer concerns and fears than their counterparts.
What if you spend much of your time thinking about a lot of issues that concern you? You will spend less time taking action to solve these problems.
Most of us want to be wealthy, but most of us do not spend the time, energy, and money required to enhance our chances of realizing this goal.
Millionaires believe that financial independence is more important than displaying high social status.
If your goal is to become financially secure, you’ll likely attain it. But if your motive is to make money to spend money on the good life, … you’re never gonna make it.
Mr. Allan recognizes that many status artifacts can be a burden, if not an impediment, to becoming financially independent. Life has its own burdens. Why add excess baggage?
The typical millionaire in our survey (one in the 50th percentile) spent about $29,000 for his most expensive motor vehicle. This equates to less than 1 percent of his net worth.
Three-year depreciation
Gift receivers … the adult children of the affluent feel that their parents’ wealth/capital is their income … income to be spent.
Most people in this country are not the entrepreneurial type. But this does not mean that they can’t become millionaires.
Whatever your income, always live below your means.
What can you give your children to enhance the probability that they will become economically productive adults? In addition to an education, create an environment that honors independent thoughts and deeds, cherishes individual achievements, and rewards responsibility and leadership. Yes, the best things in life are often free.
Teach your own to live on their own.
Consider for a moment that you are a typical affluent parent. You noted that your oldest son or daughter even at an early age was extremely independent, achievement-oriented, and well disciplined. Your instinct is to nurture these traits by not trying to control his or her decisions. Instead, you spend more time helping your less resourceful child make decisions, or you actually make decisions for him. With what result? You strengthen the strong child and weaken the weak.
Suppose you have a ten-year-old child who goes in for a physical checkup. The examining physician tells you that your son or daughter is underweight and underdeveloped. How would you respond if the parent encouraged his child to eat less and exercise less?
The more dollars adult children receive, the fewer dollars they accumulate, while those who are given fewer dollars accumulate more.
Their goal was to have a daughter who would “never have to worry.” But the method they used yielded just the opposite result. People often attempt to shelter their children from the economic realities of life. But such shelters often produce adults who are in constant fear of tomorrow.
Courage can be developed. But it cannot be nurtured in an environment that eliminates all risks, all difficulty, all dangers.
You’ll be surprised how many sales calls you can make when you have no alternative except to succeed.
After even just a few years of receiving aggressive and overbearing economic outpatient care, Beth and her husband have lost much of their ambition, economic self-confidence, and independence.
Rules for independent children:
-
- Never tell children that their parents are wealthy.
- No matter how wealthy you are, teach your children discipline and frugality.
- Be tough … life is.
- Assure that your children won’t realize you’re affluent until after they have established a mature, disciplined, and adult lifestyle and profession.
- Minimize discussions of the items that each child and grandchild will inherit or receive as gifts.
- Never give cash or other significant gifts to your adult children as part of a negotiation strategy.
- Stay out of your adult children’s family matters.
- Don’t try to compete with your children.
- Always remember that your children are individuals.
- Emphasize your children’s achievements, no matter how small, not their or your symbols of success.
- Tell your children that there are a lot of things more valuable than money.
I am not impressed with what people own. But I’m impressed with what they achieve.
Always strive to be the best in your field…. Don’t chase money. If you are the best in your field, money will find you.
Yes, you are more likely to become affluent if you’re self-employed. But what some of these reporters don’t tell you is that most business owners are not millionaires and will never come close to becoming wealthy.
They can take your business, but they can’t take your intellect!
PAWs need to achieve, to create wealth, to become financially independent, to build something from scratch. UAWs more often need to display a high-status lifestyle.
Ich hoffe, dass Dir meine Notizen geholfen haben. Weitere Zusammenfassungen findest du auf GetAbstract. GetAbstract bietet Buchzusammenfassungen an, auch als Hörbuch. So kannst du während eines einstündigen Workouts 6 Bücher hören! Nach 10 Minuten weißt du, ob sich das Buch für dich lohnt. Dabei geht es aber nicht nur um Geld, sondern auch um Deine Lebenszeit! Probiere es jetzt kostenlos aus. Und wenn du das gesamte Buch als Hörbuch haben möchtest, dann hol dir jetzt gleich dein kostenloses Hörbuch bei Audible. Dort kannst du dir fast jedes Hörbuch im kostenlosen Probeabo herunterladen.
Bildquelle: Pexels, CC0 Creative Commons


Hinterlasse einen Kommentar
An der Diskussion beteiligen?Hinterlasse uns deinen Kommentar!